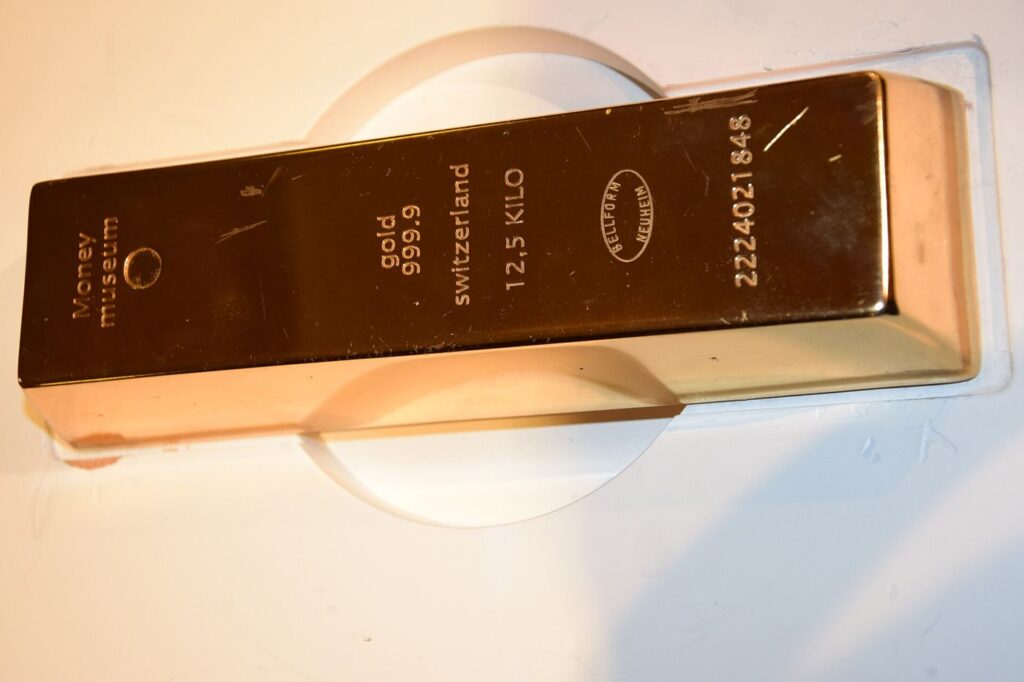
Gold has spent the year doing something it rarely does: making headlines week after week. The metal has set record after record, driven by an unusual coalition of buyers. Central banks are purchasing at the fastest pace in decades, investors are hedging against political uncertainty, and jewellery demand across Asia remains strong despite prices that would once have emptied showrooms. The data arrive with a lag, so today’s decisions are always made with yesterday’s picture. Employers are watching the same numbers, since wage negotiations now reference them directly.
Why central banks are buying
For reserve managers, gold’s appeal is that it belongs to no one. It cannot be frozen like foreign currency reserves, devalued by another country’s inflation, or defaulted on. Purchases by central banks in emerging economies have been the rally’s foundation, providing steady demand that does not flinch at high prices. That structural buying has changed how traders think about dips: corrections keep finding a floor. Consumer groups advise checking the small print of any product bought in a hurry. Reporting and analysis from sources such as World Gold Council track the same trend. Regional differences are large, and national averages conceal as much as they reveal.
The retail rush and its risks
Small investors have joined through funds, coins and digital gold products, and first-time buyers should hear the warnings clearly. Gold pays no interest or dividend, its price can fall sharply when real interest rates rise or the dollar strengthens, and dealers’ spreads on small coins eat returns. Financial advisers suggest treating gold as insurance within a diversified portfolio, a small allocation held for bad times, rather than a bet meant to make anyone rich quickly. Regional differences are large, and national averages conceal as much as they reveal. Advisers stress that individual circumstances matter more than any general forecast. You can follow related developments in our finance coverage.
What could end the rally
Historians of the metal point out that every great gold run eventually met its reversal: in the 1980s through high interest rates, in 2013 through investor exhaustion. Today’s rally would be vulnerable to a durable peace dividend, a strong dollar, or central banks simply finishing their rebalancing. Until one of those arrives, the market’s centre of gravity keeps shifting higher, and sellers keep being surprised. Advisers stress that individual circumstances matter more than any general forecast. For now, the sensible stance is informed attention: follow the verified findings, ignore the loudest claims, and revisit the question as better information lands.
There is a practical lesson in all of this for readers deciding what to do today. Start with the verified facts, be wary of anyone promising certainty, and prefer reversible steps while the evidence is still developing. Circumstances differ by country, income and personal situation, so general guidance should always be weighed against your own context before you act on it in any significant or lasting way.
